One journey, age 3 to 18
Money skills grow with your kid.
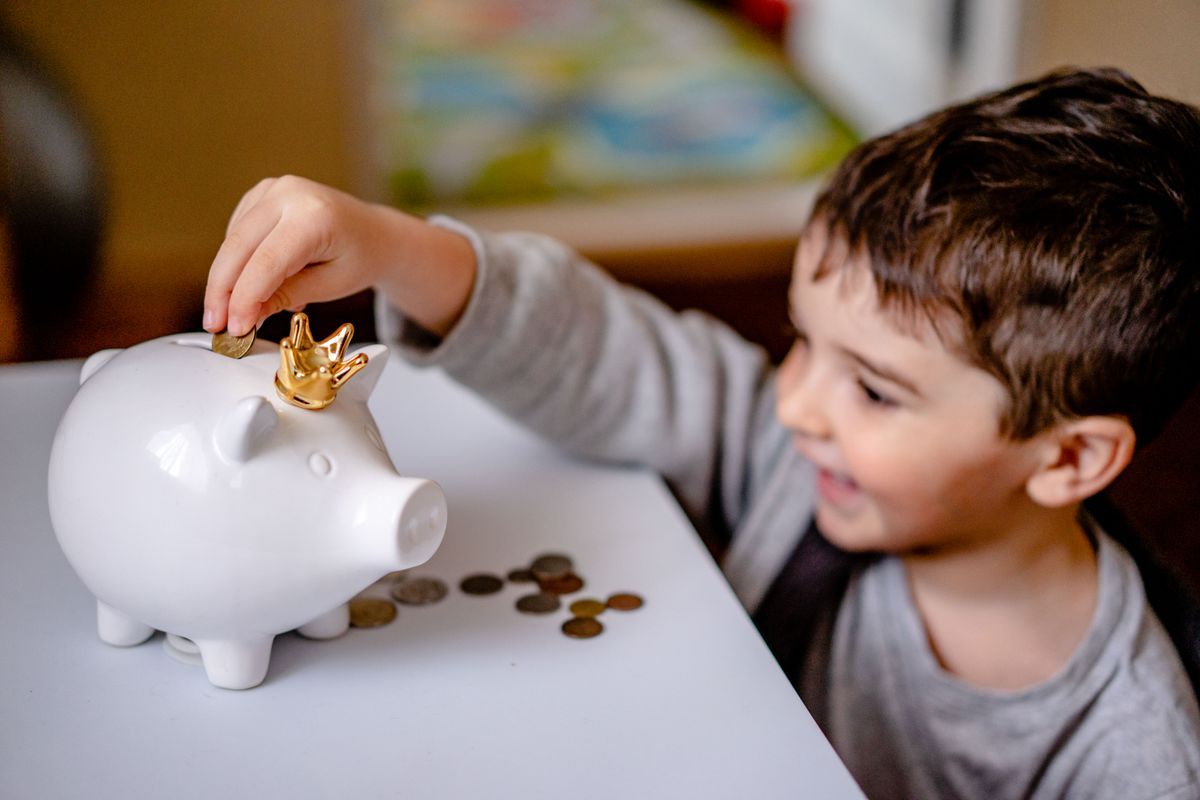
Nobody is born knowing how money works. Kids learn it the same way they learn everything else — a little at a time, by doing it, with someone they trust beside them. Money Horizon walks your family through the whole journey, from a first piggy bank to a first paycheck.
Start where your child is right now. Every stage builds on the one before it, and every idea on this site is something you can try at home this week.
The journey
Pick your child's age to begin. If your child is new to money, start one stage earlier — the basics are quick to catch up on, and they make everything after them easier.
Save, Spend, Share
Three jars, one big idea: money has jobs. Kids learn to wait, to choose, and to give a little away — all before they can read a price tag.
Allowance & Chores
Real money, real choices. How to set up an allowance that teaches instead of just spends, and how to save up for something they actually want.
Budgeting, Earning & Growing
A first budget, first ways to earn, and the quiet superpower of compound interest — the earlier money starts growing, the harder it works.
Investing, Working & Adulting
Investing basics, the custodial Roth IRA, a first job and first paycheck, a bank account, and the needs-versus-wants habit that carries into adult life.
A guide for grown-ups
How to talk about money without lectures, how much allowance makes sense, and how to use this site together — ten minutes at a time.
Savings & growth calculators
A savings goal tracker that shows how many weeks until the goal, a compound interest calculator that shows what steady saving can become, and an allowance planner that splits a weekly allowance into spend, save, and share.
Why start early
Money habits are like any other habits: the earlier they start, the more natural they feel. A child who practices waiting for a toy at age 5 is practicing the same skill an adult uses to wait for a bigger purchase at 35. A teenager who has been splitting a paycheck for two years doesn't need a lecture about budgeting — they've been doing it.
Starting early has three quiet advantages:
- Mistakes are cheap. A $5 mistake at age 8 teaches the same lesson as a $500 mistake at 28 — but it costs a hundred times less.
- Time is on their side. Money saved or invested young has the most years to grow. A teenager's dollar has decades of runway that an adult's dollar doesn't.
- Talking about money becomes normal. Families that talk about money a little bit, regularly, raise kids who aren't afraid of it — and who ask questions instead of guessing.
You don't need to be an expert, and you don't need a lot of money yourself. You need ten minutes, a real example, and a willingness to say "let's figure this out together."
What each stage teaches
Each stage has one main job. You don't have to do everything on a page — the main job is the one to get right.
- Ages 3–6 — money has jobs. Save, spend, share. The three jars make an invisible idea visible, and waiting for a small goal is the first real money skill.
- Ages 6–10 — money is mine to manage. A regular allowance turns money from something adults hand out into something kids plan with. They learn to save for a goal, tell a need from a want, and survive a small mistake.
- Ages 10–14 — money has a plan. A first budget, first ways to earn, and compound interest — the idea that money can grow on its own if you give it time.
- Ages 13–18 — money is real now. Investing basics, a first job and paycheck, a bank account, and the custodial Roth IRA — the account that turns teenage earnings into a decades-long head start.
- For parents — how to talk about it. Scripts for hard questions, allowance guidance by age, and the common mistakes to avoid.
- Tools — try the numbers. A savings goal tracker, a compound interest calculator, and an allowance planner your child can play with. No sign-up, nothing saved.
If your child is starting late, that's fine — start one stage back, move fast through the basics, and catch up. The stages are a path, not a deadline.
How to use this site
- Find your child's stage. Start with their age — or one stage back if money is brand new to them.
- Read it together. The pages are written so a parent and child can go through them side by side. Older kids can read on their own.
- Try one thing. Each page has something to do this week, not a course to finish. One jar, one goal, one conversation.
- Come back as they grow. The next stage is waiting whenever they're ready for it.
Common questions
When should we start?
As soon as your child notices money — usually around age 3 or 4. They don't need to count yet. They need the idea that money is limited, that waiting gets you something, and that some of it is for sharing. Start with the three jars and go from there.
How much allowance should we give?
There's no single right number. A common starting point many families use is about $1 per week for each year of age — for example, $7 a week for a 7-year-old — but the amount matters less than the regularity. Same amount, same day, every week. The full guidance, including how allowance changes as kids get older, is on the parents' page. (All amounts on this site are examples.)
Do kids need their own bank account?
Not until they're earning real money — usually around the first job, in the early teens. Before that, jars and envelopes work better, because kids can see the money. When a paycheck starts arriving, a teen checking and savings account (usually joint with a parent) is the right next step. See Ages 13–18.
What if my child spends everything right away?
Let them — and let them feel the empty week that follows. That's the lesson, and it only works if you don't rescue them with an advance. A calm "that's what next week's money is for" teaches more than any lecture. Small mistakes now are the cheap version of expensive mistakes later.
What if we don't have much money ourselves?
These lessons don't need a big allowance. The three jars work with coins. A budget works with $5 a week. And kids in tight times often learn the most valuable lesson of all: that a family can be careful with money and still be okay. Be honest at their level — "we're being careful right now, and here's our plan" — rather than pretending money isn't a worry.
Should I pay my child for chores or good grades?
Keep everyday family chores unpaid — everyone helps because we live here. Extra jobs beyond normal chores can earn extra money. And don't tie allowance to grades: grades are their own system, and mixing the two muddles both. There's more detail on this in the Ages 6–10 page and the parents' guide.
Is this site financial advice?
No. Money Horizon is general education — ideas, examples, and starting points for family conversations. For real decisions about investing, taxes, or your family's finances, talk with a qualified financial professional.
A note on the numbers: every dollar example on this site is just an example, meant to make an idea concrete. Your family's numbers will be different — that's fine. The habits matter more than the amounts.